November 16, 2026
Transparency Registry: What Corporate Groups Must Report
By Philipp Seibald
Vice President Sales
15 min read
Share this post
Since August 2021, the Transparency Register obligation has applied to every GmbH, AG and registered partnership in Germany, regardless of the commercial register. In Austria, the WiEReG also requires an annual report. For a single GmbH, this is done quickly. In a group with dozens of entities, it becomes a data problem. This guide shows who must report, which deadlines apply, what violations cost and what changes from 2027 under the EU Anti-Money Laundering Regulation.
Key facts at a glance
Who: In Germany, all legal entities under private law and registered partnerships must report their beneficial owners (Section 20 GwG).
When: In Germany “without delay”. In Austria within four weeks of registration or a change, plus annually.
Costs: The report itself is free of charge in Germany. Maintaining the register incurs an annual fee of EUR 19.80 per legal entity (TrGebV).
Fines: Up to EUR 150,000 for intent, in serious cases up to EUR 1 million (Section 56 GwG). In Austria up to EUR 200,000.
Control: Banks and other obliged entities cross-check the register. By early September 2023, 80,585 discrepancy reports had already been filed.
2027: From 10 July 2027, the EU Anti-Money Laundering Regulation applies (AMLR). Threshold “at least 25%”, changes within 28 calendar days at the latest, annual review.
In a company group: The real work lies not in the report itself, but in keeping shareholding and officer data current for every entity.
Transparency Register: What is it?
The Transparency Register is an official register that records the beneficial owners of companies. These are the natural persons who ultimately own or control a company. The register aims to make money laundering and terrorist financing harder, because owners can no longer hide behind corporate networks.
In Germany, the Transparency Register is governed by the Anti-Money Laundering Act (GwG) and has existed since 2017. The register is maintained by Bundesanzeiger Verlag, while the Federal Office of Administration is responsible for fines. In Austria, the equivalent is called the “Register of Beneficial Owners”. It is based on the Beneficial Owners Register Act (WiEReG) and is maintained by the Federal Ministry of Finance.
Who counts as a beneficial owner?
Under current German law, this is any natural person who holds more than 25 percent of the capital shares or voting rights or exercises control in a comparable way. If no one can be identified, the legal representative is deemed the “fictitious” beneficial owner. We explain in detail how to identify beneficial owners in multi-tier structures in our article on UBO – Ultimate Beneficial Owner.
What is reported?
First and last name, date of birth, place of residence, nationalities, and the nature and extent of the beneficial interest. For this, the company needs current data from the shareholder list, from trust and voting agreements, and from the ownership chains of the parent companies.
Who can access it?
Since the ruling of the European Court of Justice of 22 November 2022 (C-37/20, C-601/20), the register is no longer open to everyone. Anyone wishing to view third-party data must demonstrate a legitimate interest. Banks, notaries and other obliged entities under the GwG still have access and use it for every customer due diligence check.
Transparency Register obligation: Who must register?
In Germany, the registration obligation applies to all legal entities under private law and all registered partnerships. They must obtain, retain and keep up to date the information on their beneficial owners and report it “without delay” for entry in the Transparency Register. Not affected are sole proprietorships and unregistered GbRs.
Transparency Register obligation for the GmbH
Until 31 July 2021, the so-called notification fiction applied. A GmbH did not have to report if the information was already evident from the commercial register. The Transparency Register and Financial Information Act abolished this exemption. Since then, every GmbH must report itself, even if all shareholders are listed in the commercial register.
Transitional deadlines applied to existing companies. They expired long ago:
AG, SE, KGaA: 31 March 2022
GmbH, UG, cooperative, partnership company: 30 June 2022
all other legal forms: 31 December 2022
Transparency Register obligation in Austria
In Austria, partnerships and corporations in the commercial register, private foundations and associations, among others, are required to report. Unlike in Germany, there is a genuine exemption: a GmbH, OG or KG does not have to report if all shareholders are natural persons. This applies to the majority. As of 1 January 2023, around 392,000 legal entities were registered, over 300,000 of them exempt from the reporting obligation. The exemption no longer applies as soon as another company holds shares or a trust relationship exists. In a group of companies, it therefore generally does not apply to subsidiaries.
What this means for groups of companies
Every company in the group is itself subject to the reporting obligation. A holding company with 40 subsidiaries in Germany and Austria therefore has 40 separate obligations, each with its own deadline. The beneficial owners of a second-tier subsidiary are determined by the entire chain above it. If a shareholding changes at the top, this can trigger reports for all companies below.
Deadlines, costs and fines at a glance
Transparency Register deadline
The German GwG does not set a deadline in days. The report must be made “without delay”, i.e. without culpable hesitation. This applies to the initial report after incorporation and to every change in beneficial owners.
Austria is more specific:
Initial report within four weeks of entry in the commercial register
Changes within four weeks of becoming aware of them
Annual review with a report or confirmation within four weeks of the due date, even if nothing has changed
Transparency Register costs
The Transparency Register report itself costs nothing in Germany. Fees are charged for maintaining the register and for inspections:
Fee | Amount |
Annual fee per legal entity (from 2024) | EUR 19.80 |
Inspection per retrieved document | EUR 1.65 |
Printout by post, on request | EUR 7.50 |
For a group with 40 German companies, this amounts to just under EUR 800 per year. The amount is manageable. What makes Transparency Register entry expensive is the internal effort and errors. Be wary of letters from private providers presenting a paid registration as mandatory: there is no obligation to use such services.
Transparency Register fines
In Germany, any missing, incorrect, incomplete or late notification is an administrative offence:
up to EUR 150,000 for intent
up to EUR 100,000 for recklessness
up to EUR 50,000 in other cases
for serious, repeated or systematic violations, up to EUR 1 million or twice the economic benefit
The Federal Office of Administration publishes final fines on its website for five years. For a bank or an industrial group, this reputational damage often weighs more heavily than the amount.
In Austria, violations are financial offences. Incorrect, incomplete or late reports cost up to EUR 200,000 for intent and up to EUR 100,000 for gross negligence. Before that, the authority imposes coercive penalties. According to tax advisory firm ICON, this starts with a threatened EUR 1,000 and then rises to EUR 4,000. The Supreme Administrative Court considers poor office organisation to be gross negligence. “The letter ended up with the wrong clerk” is therefore no reliable defence.
Why the Transparency Register obligation matters to CFOs
The register is monitored, and monitoring is increasing. In 2023, the German Federal Government provided the following figures in response to a parliamentary inquiry:
Metric | Value | As of |
Registered legal entities | 1,761,695 | 31 Aug 2023 |
Administrative offence proceedings opened since February 2018 | 26,732 | 13 Sep 2023 |
Fines imposed by the Federal Office of Administration | 6,740 | 13 Sep 2023 |
Discrepancy reports 2020 | 8,857 | Full year |
Discrepancy reports 2023 | 80,585 | Until 8 Sep 2023 |
The number of discrepancy reports has thus increased almost tenfold within three years. Banks, insurers and auditors must report when their own findings differ from the register. For the audited company, this means an outdated entry will be noticed at the latest during the next credit assessment. Since January 2026, there has also been a reporting obligation for discrepancies in real estate information (Section 23b GwG), which also covers formal errors such as outdated company names.
An open discrepancy report remains visible in the register until the review is complete. According to GÖRG, the consequences for business dealings are still unclear. For a CFO, this means a register entry becomes part of the credit and KYC checks carried out by banks and business partners.
The 4 root causes of incorrect reports
Errors in the Transparency Register rarely happen on purpose. In groups of companies, we keep seeing the same four causes.
1. Shareholding data is scattered.
Shareholder lists, trust agreements and voting agreements sit with the legal department, the tax department and external law firms. No one has the complete picture.
2. Changes do not trigger a report.
A capital increase, a share purchase or a change of managing director is carried out in the commercial register. Nobody in the process knows that this also triggers a Transparency Register report.
3. The chain is not recalculated.
Shifting shares at the top of the group changes the beneficial owners of all companies below. In Excel, this chain is rarely updated in full.
4. Multiple countries, multiple rules.
Germany reports “without delay”, Austria within four weeks and annually. Managing both countries with one list means missing one of the two logics.
Not a reporting problem, but a master data problem
The Transparency Register obligation looks like a formal reporting task. The form at the Bundesanzeiger takes just a few minutes to complete. The difficulty lies beforehand: who, today, on this very day, are the beneficial owners of each individual company?
Only a current, well-maintained dataset on companies, shareholdings, officers and contracts can answer this question. It is a matter of shareholding master data. Maintaining it in one place makes Transparency Register reports a by-product. Maintaining it in scattered places means rebuilding it for every report.
Transparency Register entry in a group: 5 steps
In groups of companies, a robust process for Transparency Register entry follows five steps.
1. Record the company portfolio.
List all group companies with legal form, registered office, register and registration number. For each company, note whether it is subject to reporting in Germany, Austria or another country.
2. Map the ownership chain.
Who holds which shares and voting rights, directly and indirectly? Trust relationships, voting agreements and special rights are part of this. The shareholder list data forms the basis but is not sufficient on its own.
3. Derive beneficial owners for each company.
From the chain, determine for each company which natural person exceeds the threshold. If there is none, the legal representative is reported as the fictitious beneficial owner.
4. Define triggers.
Every capital measure, share purchase and change in management automatically checks whether a report is due. In Austria, the annual deadline per company is added.
5. Document the report.
The date, content and proof of each report are filed with the company. This allows a quick response to a discrepancy report and makes every audit traceable.
Steps 1 to 3 are a one-off effort. Steps 4 and 5 determine whether the data is still correct after six months.
How the Goldright Legal Entity Manager supports Transparency Register entry
The Goldright Legal Entity Manager addresses the point where the Transparency Register obligation becomes complex in groups of companies: the data before the report. Companies, shareholders, shares and officers are managed in one central platform instead of scattered lists. The report itself is still filed in the Transparency Register or, in Austria, via the Business Service Portal.
Make the ownership chain visible.
Subsidiaries, shareholders and shares sit in one dataset. Shareholding charts and organisational charts are generated automatically from this data. This makes the chain traceable across all levels, the basis for steps 2 and 3.Manage changes with workflows.
Data maintenance and approvals run through configurable workflows based on BPMN 2.0. A change in shares can thus automatically trigger the review step “Transparency Register affected?”.Monitor deadlines and key dates.
Deadlines are tracked in the system instead of in individual people’s calendars. This helps with prompt reporting in Germany and the annual report in Austria.Secure history and evidence.
Every change is saved with a timestamp, and documents are stored directly with the company. The structure as of any past date can be retrieved at any time. This shortens the response to a discrepancy report.Use reports and access rights.
Reports on shareholding structures and ownership thresholds provide the basis for the report. An authorisation concept controls who may view and change the personal data of beneficial owners.
Looking ahead to 2027, this becomes even more important: calculating ownership across all levels under the EU Anti-Money Laundering Regulation requires a complete, up-to-date shareholding structure. Maintaining it in the Legal Entity Manager means this foundation is already in place.
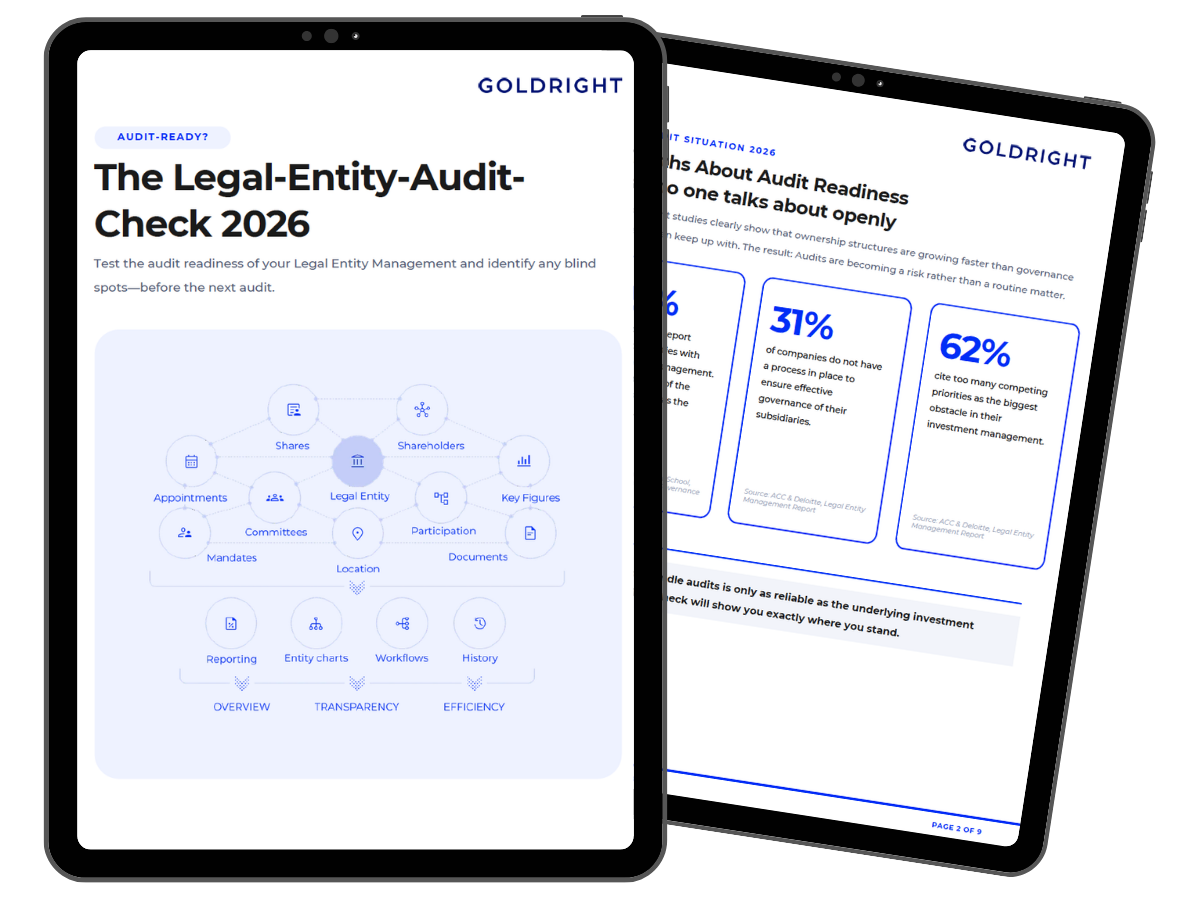
Legal Entity Audit Check: How current is your entity data?
In 15 minutes, Goldright’s Legal Entity Audit Check uses targeted questions to identify blind spots in your shareholding and entity management, and delivers prioritised recommendations.
10-step self-assessment
Prioritised recommendations per score
100% free
What changes in 2027: EU Anti-Money Laundering Regulation (AMLR)
From 10 July 2027, the EU Anti-Money Laundering Regulation (EU) 2024/1624 applies directly in all member states. It replaces many national rules on the Transparency Register. Five changes are relevant for groups of companies:
New threshold: A beneficial owner is anyone holding at least 25 percent, directly or indirectly. In Germany, the rule was previously “more than 25 percent”.
Look-through calculation instead of control chain: Shareholdings are calculated across all levels. Many existing entries will therefore need to be reassessed.
Fixed deadline: Changes must be reported “without delay and in any case within 28 calendar days”.
Annual review: Every legal entity must check at least once a year whether its information is up to date. This can be combined with the annual financial statements, for example.
More data: Place of birth, full residential address and ID number become mandatory. The German term “wirtschaftlich Berechtigter” is replaced by “wirtschaftlicher Eigentümer” (beneficial owner).
For German groups, this means the annual review already familiar in Austria is coming to Germany too. Anyone without a look-through shareholding structure by then must build one by July 2027. The details of the national implementing laws are still open. According to RAW Partner, the register has not yet issued any application guidelines either.
Transparency Register obligation compared: Germany, Austria, AMLR
The table summarises the rules for groups that manage companies in Germany and Austria.
Criterion | Germany (GwG) | Austria (WiEReG) | EU from 10 Jul 2027 (AMLR) |
Register | Transparency Register, Bundesanzeiger Verlag | Register of Beneficial Owners, BMF | Central register per member state |
Who reports | All legal entities under private law and registered partnerships | Companies, foundations, associations, trusts; exemption if all shareholders are natural persons | All legal entities |
Threshold | More than 25% | More than 25% | At least 25%, calculated across all levels |
Initial report deadline | Without delay | 4 weeks after registration | Without delay after incorporation |
Deadline for changes | Without delay | Without delay | Without delay, within 28 calendar days at the latest |
Annual obligation | None | Review and report within 4 weeks of due date | Review at least annually |
Fees | EUR 19.80 per year and legal entity | Report via USP; inspection subject to a fee | Regulated nationally |
Sanctions | Up to EUR 150,000, serious cases up to EUR 1 million | Up to EUR 200,000 (intent), coercive penalties | Regulated nationally |
Sources: Section 20 GwG, Section 56 GwG, TrGebV, BMF, Section 15 WiEReG, Art. 63 AMLR, RAW Partner.
Best practices: What works in groups of companies
One data source for all companies. Shareholdings, officers and contracts are maintained in one place. The legal, tax and finance departments draw on it instead of keeping their own lists. You know this principle from the Golden Record for customer and product data.
Clear responsibility per company. For each company, one person is responsible for the Transparency Register report, with a deputy.
Build the reporting obligation into the corporate housekeeping process. No shareholder resolution without the review step “Transparency Register affected?”.
Reconcile register extracts regularly. Once a year, compare your own entries with your internal dataset. From 2027, this is mandatory anyway.
Keep the history. Who was a beneficial owner and when must be provable retrospectively. In Austria, due diligence documents must be retained for at least five years.
Define governance. Who may change shareholding data, and who approves? The rules belong in a Data Governance Framework.
Practical scenario: One holding, 30 companies, two countries
A family holding company manages around 30 companies in Germany and Austria. The shareholding data is kept in an Excel file in the legal department. The tax department maintains a second list for tax group reporting.
After a generational change, shares in the holding are redistributed. In the commercial register, this is done within a few weeks. The follow-up reports in the Transparency Register for the subsidiaries are left undone because nobody recalculates the chain downwards. It would only have come to light at the next credit check by the house bank, as a discrepancy report.
With central shareholding management, the same process runs differently. The share transfer is recorded once. The system shows which companies’ beneficial owners change and which deadlines apply in Germany and Austria. The reports are documented with dates.
Pitfalls: What to avoid
Relying on the old notification fiction. It has no longer applied since August 2021. Entries in the commercial register do not replace a Transparency Register report.
Using the fictitious beneficial owner as the default. The legal representative may only be reported if no one can be identified after a thorough review.
Forgetting the Austrian annual report. A confirmation is due even if nothing has changed.
Falling for private “registration services”. Invoices with threatening language are not official fee notices.
Ignoring discrepancy reports. They remain visible until the review is complete.
Waiting until July 2027. The look-through calculation across all levels requires clean data, and that cannot be built in a few weeks.
Ready for 2027? Start with the Legal Entity Audit Check.
Find out which companies in your group have outdated or incomplete shareholding data, and where the new 25 percent threshold changes your reports.
10-step self-assessment
Prioritised recommendations per score
100% free
Conclusion: The Transparency Register obligation is a data task
In Germany, the Transparency Register obligation applies to every GmbH, AG and registered partnership. In Austria, there is also the annual report. The report itself is short and inexpensive. What takes effort is knowing at all times who the beneficial owner is for every company in the group.
Monitoring is increasing. Banks and other obliged entities cross-check the register with every review, and the number of discrepancy reports has risen sharply since 2020. Fines of up to EUR 150,000, and up to EUR 1 million in serious cases, are made public. From July 2027, the EU Anti-Money Laundering Regulation requires a look-through calculation across all levels, a 28-day deadline and an annual review.
Finance and compliance managers should therefore treat the obligation not as a one-off report, but as part of their legal entity management. Maintaining companies, shareholdings and officers in one place makes it possible to derive reports from the dataset and trace every change. Working with scattered lists means rebuilding the chain for every report and bearing the risk of errors.
The first step is an honest assessment: which entity data is current, which is not, and where is the link between the commercial register and the Transparency Register missing?
Frequently Asked Questions
- An official register in which companies report the natural persons who ultimately own or control them. In Germany, this is governed by the Money Laundering Act; in Austria, by the WiEReG.
- In Germany, yes. Since the elimination of the presumption of notification in August 2021, every GmbH must file its own report. In Austria, a GmbH is exempt if all of its shareholders are natural persons.
- Yes. Every company subject to the reporting requirement has its own obligation. The beneficial owners of the subsidiary are determined based on the chain of ownership above it.
- In Germany, “immediately.” In Austria, four weeks after registration or a change, plus an annual report. Starting July 10, 2027, the EU-wide rule will apply: no later than 28 calendar days after a change.
- The registration itself is free of charge. Since 2024, each legal entity has paid an annual fee of 19.80 euros for the maintenance of the register.
- In Germany, up to 150,000 euros for intentional violations, and up to 1 million euros for serious or repeated violations. In Austria, up to 200,000 euros for intentional violations.
- The company itself is required to file the report, and this is carried out by management. Shareholders must also provide the company with the necessary information. Violations of this requirement are also subject to fines.
- Banks, insurers, notaries, and other obligated parties report to the registry when their own information differs from the entry. As of early September 2023, there had been 80,585 such reports.
- No. Since the European Court of Justice ruling on November 22, 2022, members of the public must have a legitimate interest. Government agencies and obligated entities continue to have access.
- The threshold will be “at least 25 percent” instead of “more than 25 percent”; ownership interests will be calculated across all levels; and an annual review will become mandatory.
- By maintaining a centralized database of companies, equity interests, and governing bodies. This database can be used to identify the beneficial owners for each company and to document disclosures in a traceable manner.
Sources
gesetze-im-internet.de: Section 20 GwG – Transparency obligations
gesetze-im-internet.de: Section 56 GwG – Provisions on fines
gesetze-im-internet.de: Anti-Money Laundering Act, full text (Section 3)
gesetze-im-internet.de: Transparency Register Fee Ordinance, annex
German Federal Government response: Bundestag printed paper 20/8480
German Federal Government response: Bundestag printed paper 21/5416
IHK Gießen-Friedberg: The Transparency Register: Registration obligation for companies
firma.de: Transparency Register – reporting obligation, registration, FAQ
GÖRG: Transparency Register: More clarity, but new practical uncertainties
Noerr: ECJ: Public access to national Transparency Register violates EU fundamental rights
Austrian Federal Ministry of Finance: The Register of Beneficial Owners
Business Service Portal: Register of Beneficial Owners (WiEReG)
ICON Wirtschaftstreuhand: WiEReG: Annual reporting obligations must be observed
Forum Media: Section 15 WiEReG – Penal provisions
KPMG Tax News: Federal Finance Court case law on WiEReG reporting violations
Official Journal of the EU: Regulation (EU) 2024/1624, Art. 63
RAW Partner: New Transparency Register rules from July 2027